Credit Reset Roadmap: How to Find Hidden Issues and Strengthen Your Financial Profile
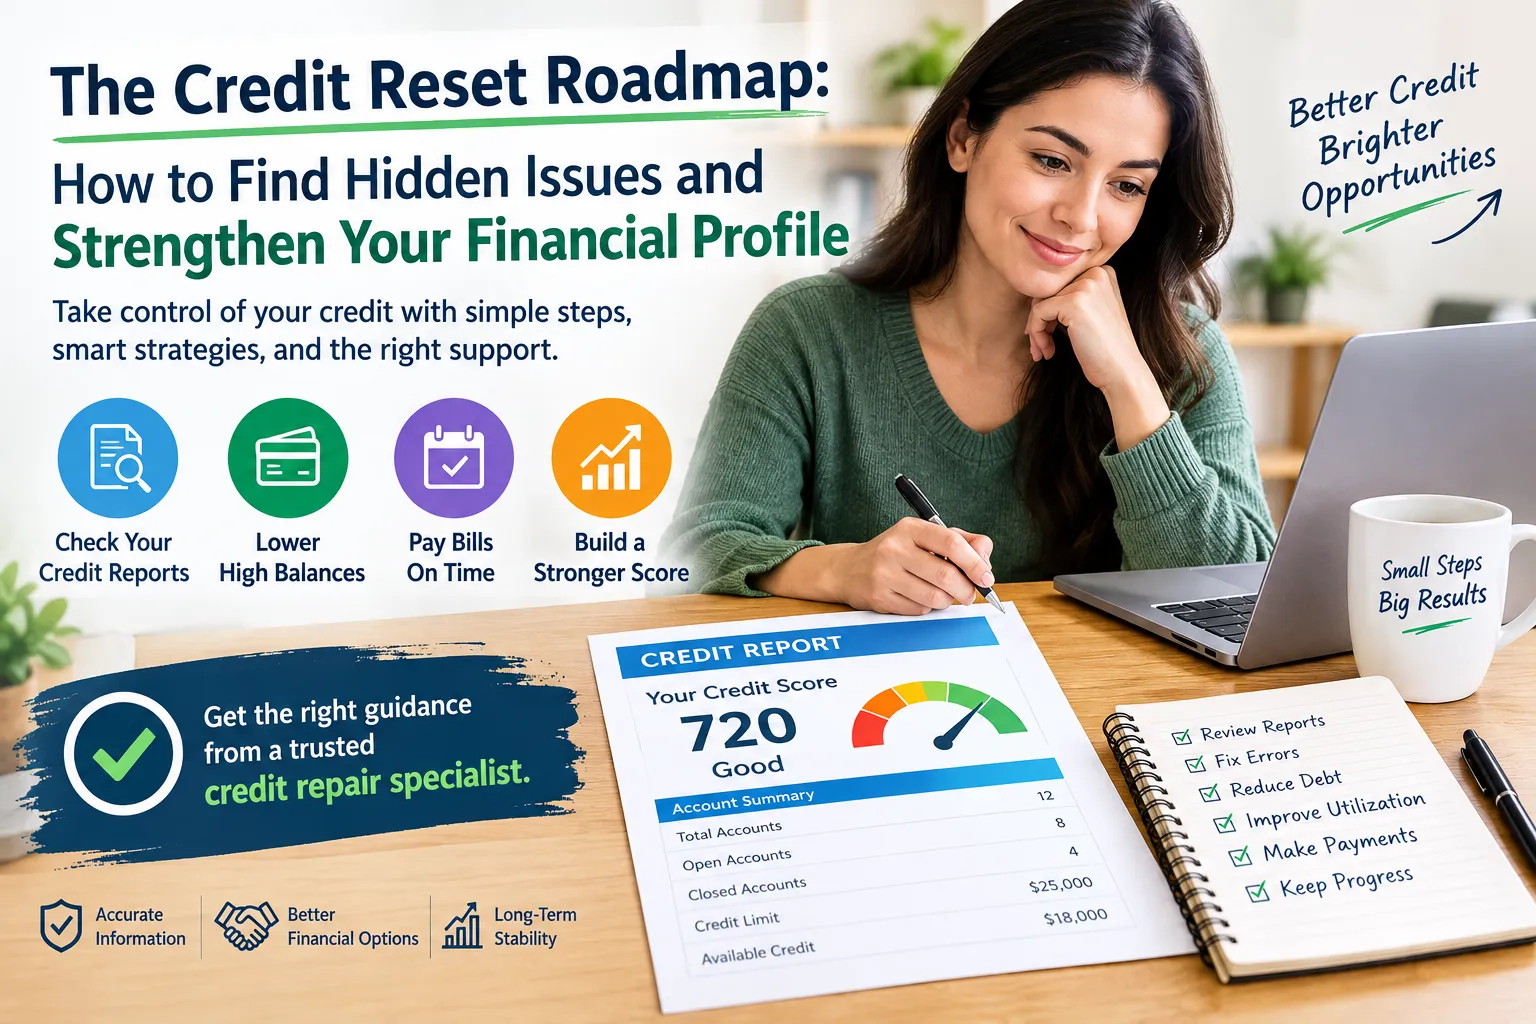
A disappointing credit score can affect more than your ability to qualify for a credit card. It may influence financing opportunities, loan terms, housing applications, insurance decisions, and other financial goals. When your credit profile has negative marks or inaccurate information, the problem can feel overwhelming, especially when you do not know which issue deserves attention first.
The good news is that improving your credit does not require guessing. A systematic approach can help you understand what is appearing on your credit reports, identify areas that need attention, and build better financial habits over time.
Rather than looking for a quick fix, think of credit improvement as a roadmap. Each step addresses a different part of your financial profile and helps you make informed decisions.
Step 1: Identify the Real Reason Your Credit Is Weak
Before taking action, determine what is actually affecting your credit. A low score can have multiple causes, and the right solution depends on the underlying problem.
For example, one consumer may have several late payments, while another may have high credit card balances. Someone else may discover an account that does not belong to them.
Review your credit reports and look for:
- Late or missed payments
- High revolving account balances
- Collection accounts
- Charge-offs
- Accounts you do not recognize
- Incorrect balances
- Duplicate information
- Incorrect account status
- Personal information that is inaccurate
Do not assume that every negative item is an error. The purpose of reviewing your reports is to separate accurate information from information that may need correction.
Step 2: Check Your Credit Reports for Errors
One of the most practical credit improvement steps is checking whether the information being reported about you is accurate.
Compare account names, balances, payment records, dates, credit limits, and account status. If something appears incorrect, gather documents that support your position.
For example, if an account shows a balance that you believe is wrong, keep statements or payment records that may help establish the correct information.
When a legitimate error is discovered, consumers can generally dispute inaccurate information with the appropriate credit reporting agency and, when appropriate, the company that supplied the information.
Keeping organized records is important. Save copies of disputes, supporting documents, responses, and relevant account statements.
Step 3: Deal With High Credit Card Balances
High revolving balances can make it difficult to improve credit score results. Even when payments are being made on time, carrying substantial balances relative to available credit may work against a healthier credit profile.
Start by listing each credit card's current balance, limit, interest rate, and minimum payment. This gives you a clear picture of where your revolving debt stands.
Then create a repayment strategy that fits your budget. You might prioritize the card with the highest interest rate or focus on eliminating a smaller balance first to create momentum.
The important point is consistency. Avoid taking on new debt simply to make your current balances appear smaller.
Step 4: Make Payment History a Priority
A strong credit profile is built through repeated responsible behavior. Missing one payment can create problems, while a long pattern of on-time payments can demonstrate financial reliability.
Create a system for every recurring bill. Automatic payments can help prevent missed due dates, while calendar reminders can provide an additional safeguard.
If automatic payments are not practical, maintain a simple monthly checklist containing each creditor, payment amount, and due date.
When your budget is tight, prioritize required payments and contact creditors before a payment becomes seriously delinquent. Early communication may provide options that are not available later.
Step 5: Be Careful About Applying for New Credit
When consumers have poor credit, it can be tempting to apply for several new accounts in an attempt to rebuild their profile. This approach can create additional inquiries and may result in accounts that are difficult to manage.
Instead, consider whether new credit is genuinely necessary.
If you already have accounts that are being managed responsibly, focus on strengthening those accounts before pursuing additional borrowing. Credit improvement is not a competition to collect as many accounts as possible.
A smaller number of well-managed accounts can be more useful than numerous accounts that increase financial pressure.
Step 6: Understand What a Credit Fixing Service Can and Cannot Do
A credit fixing service may help consumers organize the process of reviewing credit reports and addressing potentially inaccurate information. Depending on the provider, services may include credit report analysis, dispute assistance, documentation guidance, and credit education.
However, consumers should maintain realistic expectations.
No legitimate service should guarantee that every negative item will disappear or promise a specific credit score increase. Accurate negative information generally cannot simply be erased because it is unfavorable.
Before hiring a provider, review the company's services, costs, agreements, cancellation terms, and claims. A transparent provider should explain the process instead of selling unrealistic results.
Step 7: Know When a Credit Repair Specialist May Be Useful
Some credit reports are relatively straightforward. Others contain years of account history, collections, disputes, multiple creditors, and reporting discrepancies.
In more complicated situations, a credit repair specialist may help you understand the information and organize the next steps.
A specialist can potentially help identify questionable information, explain credit-report terminology, organize documentation, and guide consumers through appropriate dispute procedures.
Professional assistance should complement—not replace—good financial habits. If accurate debt remains unpaid, new late payments continue, or credit card balances remain high, correcting a reporting error alone may not solve the broader problem.
Step 8: Build Habits That Protect Your Progress
Fixing existing credit problems is only part of the process. Once improvements begin, protecting them becomes equally important.
Consider creating a simple financial routine:
- Review account balances regularly.
- Pay every required bill on time.
- Monitor revolving credit utilization.
- Avoid unnecessary borrowing.
- Review credit reports periodically.
- Keep important financial records organized.
- Maintain an emergency fund when possible.
These habits can reduce the likelihood of repeating the same credit problems.
What If Your Credit Score Does Not Increase Immediately?
Credit improvement is not always reflected instantly. Different credit reporting and scoring processes can take time to reflect changes.
If you have paid down debt or corrected inaccurate information but do not see an immediate change, do not automatically assume your efforts failed.
Review what has actually changed in your reports. Check whether balances have been updated, whether disputed information was corrected, and whether new negative information has appeared.
The goal should be to improve the underlying credit profile rather than chase daily score fluctuations.
Create a Realistic Credit Improvement Timeline
Instead of asking how quickly you can fix your credit, ask what you can consistently improve over the next several months.
During the first stage, focus on understanding your reports and identifying problems. Next, address legitimate inaccuracies and establish reliable payment habits. Then concentrate on reducing debt and maintaining manageable credit utilization.
This approach creates measurable milestones without depending on unrealistic promises.
Best Credit Strategy Is Built Around the Problem
There is no single solution that works for every credit profile. A person with inaccurate reporting needs a different approach from someone whose primary challenge is excessive debt or repeated late payments.
Start by identifying the problem. Review your reports carefully, correct legitimate inaccuracies, manage revolving balances, make payments consistently, and avoid unnecessary applications for new credit.
If your situation is complicated, a reputable credit repair specialist or credit fixing service may provide structure and education. Just remember that long-term improvement comes from combining accurate credit reporting with sustainable financial behavior.
A healthier credit profile is not created by one dramatic action. It is built through informed decisions, consistent habits, careful monitoring, and patience. By following a practical roadmap, you can move from simply worrying about your credit to actively managing it.

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Romaian
 Portuguese (Brazil)
 Greek