Preparing for Each Stage of a Funeral Home Financing Deal
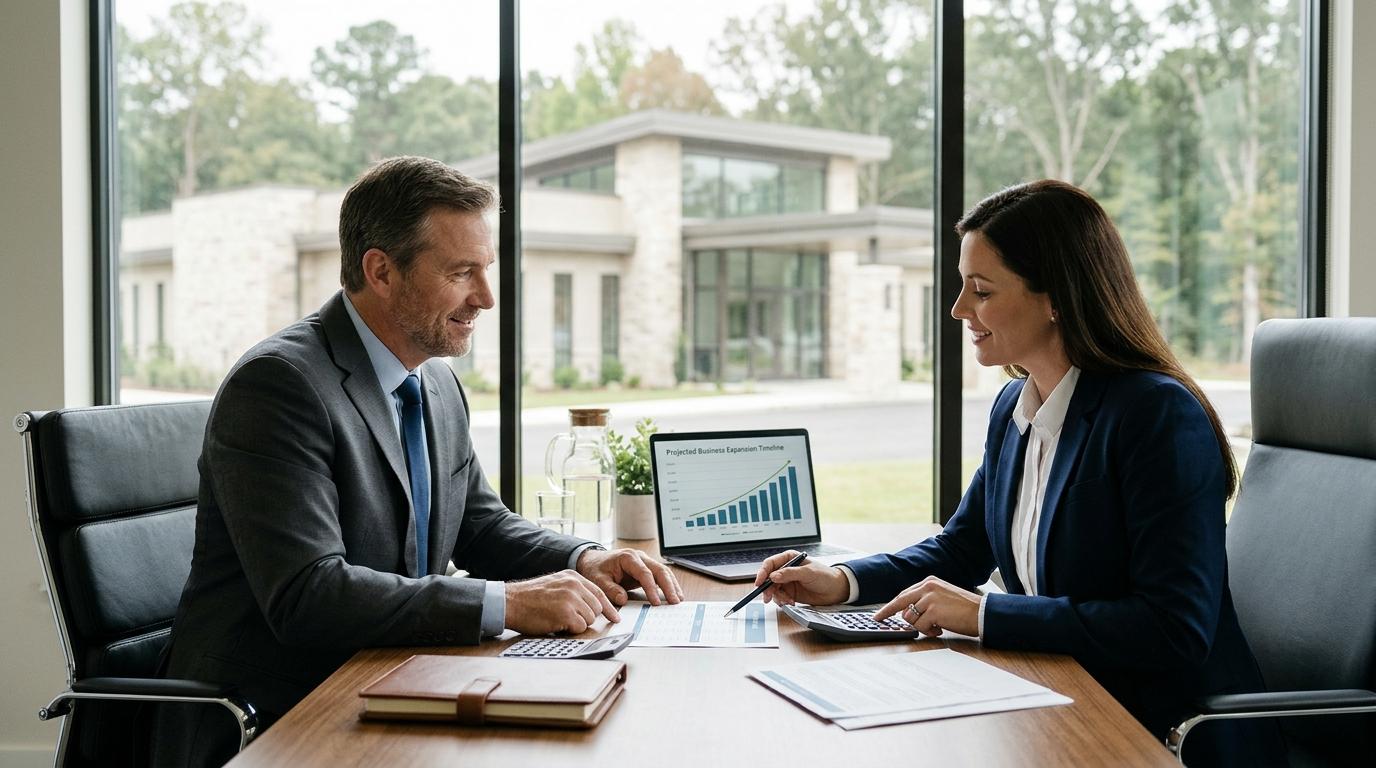
Financing a funeral home is rarely a one-step process. Whether an owner is purchasing an established business, expanding an existing location, refinancing debt, or investing in new equipment, a successful financing deal requires preparation at several stages.
Understanding the process in advance can make conversations with lenders more productive and reduce unexpected delays. It can also help owners identify financial issues before they become obstacles.
A clear business funding timeline gives borrowers a practical framework for organizing documents, evaluating financing options, responding to lender requests, and preparing for closing. While every transaction is different, most funeral home financing deals follow a recognizable progression.
1. Start With Financial and Business Planning
The first stage begins well before an application is submitted. Owners should clearly define why they need financing and how much capital the project requires.
For an acquisition, this may include the purchase price, working capital, closing costs, real estate, equipment, and renovation expenses. An existing funeral home seeking expansion may need financing for vehicles, technology, facility improvements, cremation equipment, or additional property.
At this stage, borrowers should review revenue, operating expenses, existing debt, cash flow, owner compensation, and available assets. Understanding these numbers helps determine a realistic borrowing amount.
It is also useful to establish a personal financial picture. Lenders may review personal credit, liquidity, assets, liabilities, and other financial obligations depending on the financing structure.
Good loan preparation guidance starts with knowing exactly what the business can reasonably support rather than choosing a loan amount first and trying to justify it later.
2. Organize Documents Before Applying
Once the financing objective is clear, the next step is documentation.
Lenders typically need enough information to understand the business's financial performance, ownership structure, assets, liabilities, and ability to repay the proposed loan. The exact requirements vary by lender and loan program, but borrowers should be prepared to provide items such as business tax returns, financial statements, bank statements, debt schedules, personal financial statements, and ownership information.
For an acquisition, additional documents may include the purchase agreement, historical financial statements from the target business, real estate information, equipment details, and projections.
Preparing these materials early can significantly improve the business funding timeline. Instead of spending weeks searching for missing records after submitting an application, the borrower can respond quickly when the lender requests additional information.
A well-organized document package also demonstrates that the owner understands the business and takes the financing process seriously.
3. Compare Financing Options and Work With the Right Lender
The third stage involves evaluating financing options.
Different funeral home transactions may require different structures. Acquisition financing, commercial real estate financing, equipment financing, refinancing, and working-capital funding can have different requirements and repayment structures.
Borrowers should compare more than the advertised interest rate. Important considerations may include loan term, amortization, collateral requirements, guarantees, fees, prepayment provisions, equity requirements, and the lender's experience with similar businesses.
This is where understanding the funeral financing stages becomes especially helpful. A lender that understands the economics of funeral homes may be better positioned to evaluate recurring revenue, seasonal patterns, real estate, equipment, and other industry-specific factors.
The goal is to find financing that fits the transaction rather than simply accepting the first available offer.
4. Navigate Underwriting and Lender Review
After an application is submitted, the lender moves into underwriting. This is often one of the most important stages of the process.
The lender may evaluate historical cash flow, debt-service capacity, credit history, collateral, management experience, ownership structure, and the overall strength of the transaction.
For an acquisition, the lender may also analyze whether the projected business performance can support the proposed debt. If real estate is included, property value and condition may become part of the review. Environmental or appraisal reports may also be required depending on the transaction.
Borrowers should expect questions during underwriting. Additional documentation or explanations do not necessarily mean something is wrong. Often, the lender simply needs clarification before making a final decision.
Fast and accurate responses can keep the business funding timeline moving. Delays commonly occur when requested documents are incomplete, inconsistent, or difficult to obtain.
5. Prepare for Approval, Conditions, and Closing
Loan approval is an important milestone, but it is not always the final step.
A lender may issue an approval subject to specific conditions. These could involve updated financial statements, insurance, appraisals, legal documents, collateral verification, ownership documentation, or other requirements.
Borrowers should carefully review the proposed loan structure before closing. This is the time to understand the interest rate, payment schedule, maturity date, fees, collateral, guarantees, covenants, and other obligations.
For a business acquisition, the closing process may involve several parties, including the buyer, seller, lender, attorneys, accountants, title professionals, and insurance providers.
Good loan preparation guidance includes planning for these closing requirements rather than assuming approval automatically means funds are immediately available.
Keeping communication organized during this stage can help prevent last-minute surprises.
6. Manage the Business After Funding
The financing process does not end when the loan closes. The post-closing period is another important part of the funeral financing stages.
Once funds are received, owners should use the capital according to the agreed financing purpose and maintain accurate financial records. Loan payments should be incorporated into monthly cash-flow planning.
Business owners should also monitor key performance indicators such as revenue, operating margins, debt obligations, cash reserves, and debt-service coverage. If the financing supported an acquisition or expansion, actual performance should be compared with the original projections.
Maintaining strong financial records can also make future refinancing or expansion easier. A business that consistently demonstrates organized accounting and responsible debt management may be better positioned when it needs additional capital.
Ultimately, successful financing is not simply about getting approved. It is about creating a financing structure that the funeral home can comfortably manage over time.
Conclusion
A funeral home financing deal becomes easier to manage when owners understand what happens at each stage. From defining the financing need and organizing documents to lender underwriting, approval, closing, and post-closing management, every step contributes to the overall outcome.
A realistic business funding timeline, thorough documentation, and proactive communication can help reduce unnecessary delays. At the same time, comparing financing structures carefully ensures that the loan supports the business rather than creating avoidable financial pressure.
Whether the goal is acquisition, expansion, refinancing, or investment in new assets, thoughtful preparation can make the financing process more predictable. By approaching each of the funeral financing stages strategically, owners can move forward with greater confidence and build a stronger financial foundation for the future.

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)